Europe’s Deep Tech Wave
Why Europe is early this time
Somewhere around 2018, I invited ETH's quantum professor Jonathan Home to SIX Group. I built and ran an open innovation series there called "Genie in the Bottle" – genius brains, good wine, one emerging technology per evening. The question I put to him was simple: is quantum computing relevant for the Swiss financial industry, and is it ready?
The honest answer back then: not really, and nobody knows when.
8 years later, I was at an event watching startups present real applications of quantum technology and minutes later I talked to a family business owner who runs a sports streaming platform. He told me that if quantum computing were ready, he could finally build what today is computationally out of reach: truly individual subscription models, pricing shaped around what each single customer actually wants to watch.
What struck me that evening wasn't the technology or the startup pitches. It was that a legacy owner knew precisely how this could enable his business model.
One Insight
For once, Europe is early. We've all internalized the story: Europe invents, America commercializes, and the margin leaves the continent. That's how the software era went, we experienced it as customers of someone else's stack. The current wave looks different.
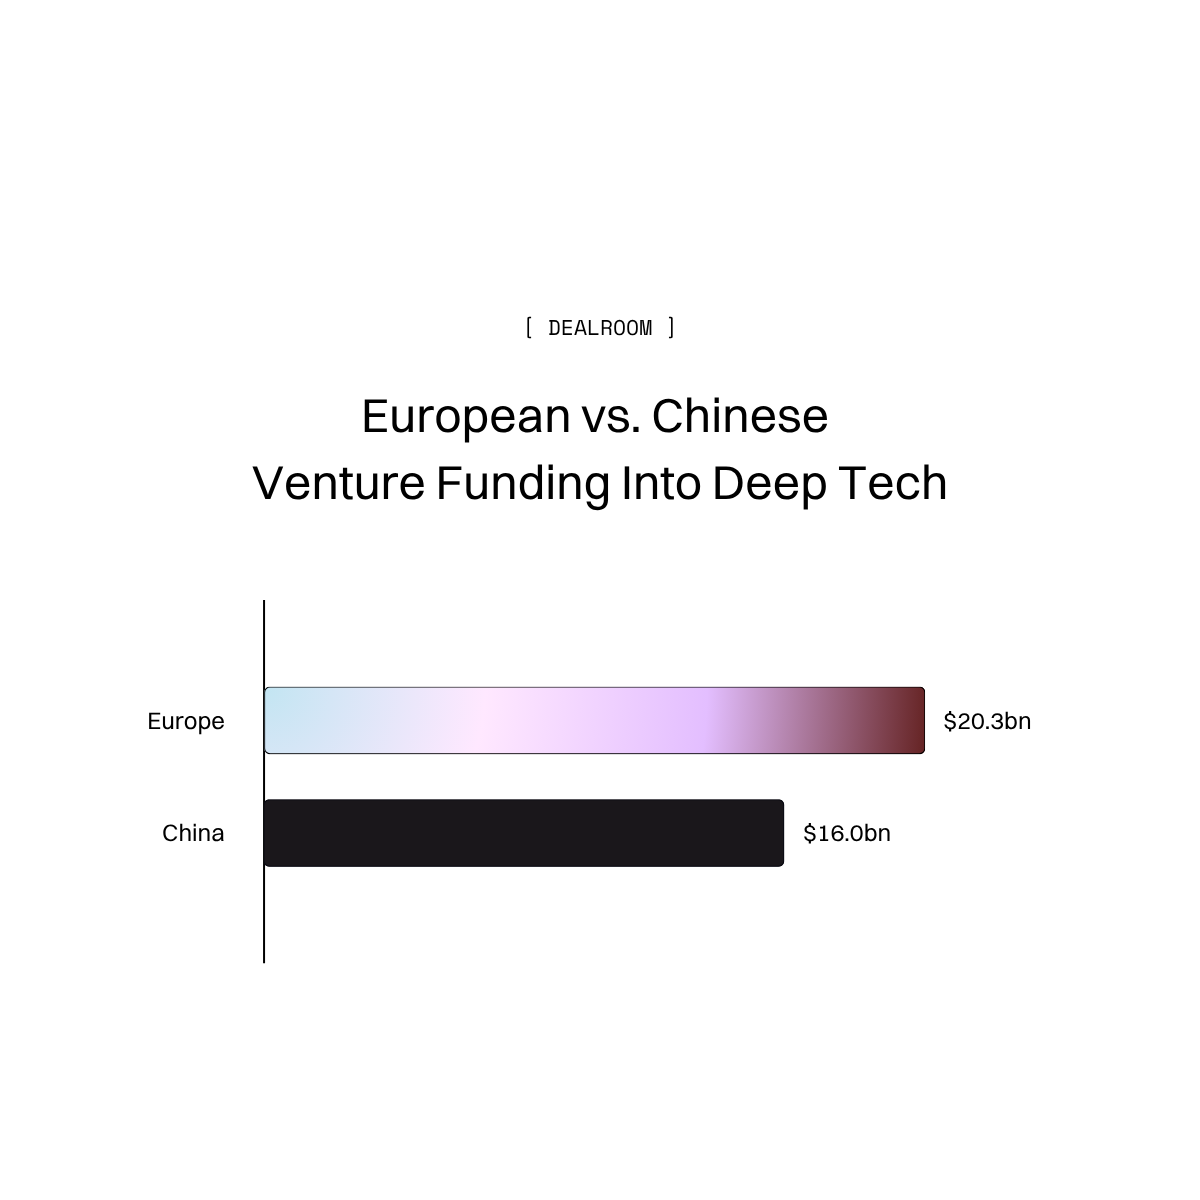
Deep tech – quantum, fusion, new materials, robotics, biotech – now attracts roughly a third of all European venture capital, and in absolute terms Europe put more into deep tech last year than China. Europe leads global funding share in quantum software and holds around 44% of the global share in advanced materials. A few weeks ago, Munich-based Proxima Fusion closed €411 million – the largest round in European fusion history, with Google and RWE investing – to build toward Europe's first commercial fusion plant. And if you're reading this from Switzerland or southern Germany: the corridor from Zurich to Lausanne to Munich alone holds over a thousand venture-backed deep tech startups.
There's a structural reason this wave suits Europe. It's physical. Reactors, chips, materials, machines – things that demand engineering depth and industrial patience. This game is being played on the home turf of Europe's industrial economy. Which means, for the first time in a generation, the technologies that will rebuild European value chains are being built next door to the businesses whose value chains they'll rebuild.
The question is not "which technology wins" – it's "whose value chain gets rebuilt first".
Many owners treat technology trends as one undifferentiated cloud: too much noise, none of it urgent, all of it somebody else's problem. But these fields don't arrive everywhere at once. Each one rebuilds specific value chains, on its own clock.
→ AI is rebuilding every knowledge-heavy process right now, sales, service, engineering, administration. The clock reads today.
→ Quantum rebuilds anything that lives on hard optimization: pricing, risk, logistics, scheduling. Pilots are running in finance, pharma, and logistics, and Europe is unusually well positioned, but realistic commercial timelines sit around five to ten years. The clock reads: this decade, not this year.
→ Energy technologies – fusion among them – rebuild the cost structure of everything energy-intensive: manufacturing, chemicals, materials processing. The fusion demonstrators are targeted for the early 2030s. A long clock, but if energy is a top-three cost line for you, a decisive one.
→ Biotech and new materials rebuild what products are actually made of – food, packaging, components, coatings.
Two questions turn this from noise into a map. Does the field reach my value chain – as an input, a process, or a substitute for what I sell? And when?
What we actually see
In our work, the failure mode is rarely ignorance of the trends. Owners read the same headlines everyone does. The failure mode is that exposure and clock never get separated: everything feels either hyped or distant, so nothing produces a decision.
And where nothing produces a decision, there is usually no structure that could hold one. Most legacy businesses have opinions about technology, but no innovation portfolio, no deliberate set of bets, spread across near-term and long-term horizons, placed through different vehicles. A pilot with a startup here, a partnership there, perhaps a small investment or a venture of your own where the exposure justifies it. Not one big bet, and not zero bets. A portfolio, sized to what your risk allows.
Bottom line
Europe's next opportunities are not a list of technologies to bet on. The wave has finally started at home, and it will rebuild value chains one by one, each on its own clock. Without an innovation portfolio – real bets, placed through real vehicles – the turn arrives on someone else's schedule. That's the quiet danger of a strong core: it feels good for a long time. Until, at some point, it doesn't.
One Question
Which of these fields reaches your value chain first – and do you know that, or do you assume it?
One Opportunity
Save the date! Family Business meets Venturing
Breakfast at ViCAFE Roastery, Zurich on Friday, October 30, 9–11am.
Hosted by Dawn Ventures, together with FBN Switzerland and special guests Damian Felchlin from Felchlin Chocolate, Cristina de Mendieta from MCI and Gota Ventures and last but not least, Noah Ghisleni from Forlam Ventures.
Everything in this issue comes down to one move: getting family businesses and the venture world into the same room. So we're doing exactly that. A morning of coffee and honest conversation about what happens when family businesses go venture, with nextgens who have sat on both sides of the table.
Formal invitations will follow.
Until Thursday in two weeks,
Lisa